Boeing's Record $745 Billion Backlog Can't Speed Up the 737 Ramp
A nearly break-even quarter, full 737 MAX certification, and a $745 billion backlog still weren't enough. Boeing pushed the 52-a-month ramp to late 2027, and the stock fell 10%.
Boeing's third-quarter numbers read like a company moving toward stability on paper, but the market treated the quarter as a disappointment. Revenue and cash flow improved, the last of the 737 MAX family won FAA certification, and the company posted a record $745 billion backlog, yet the underlying production story shifted again and the stock tumbled roughly 10% on the day.
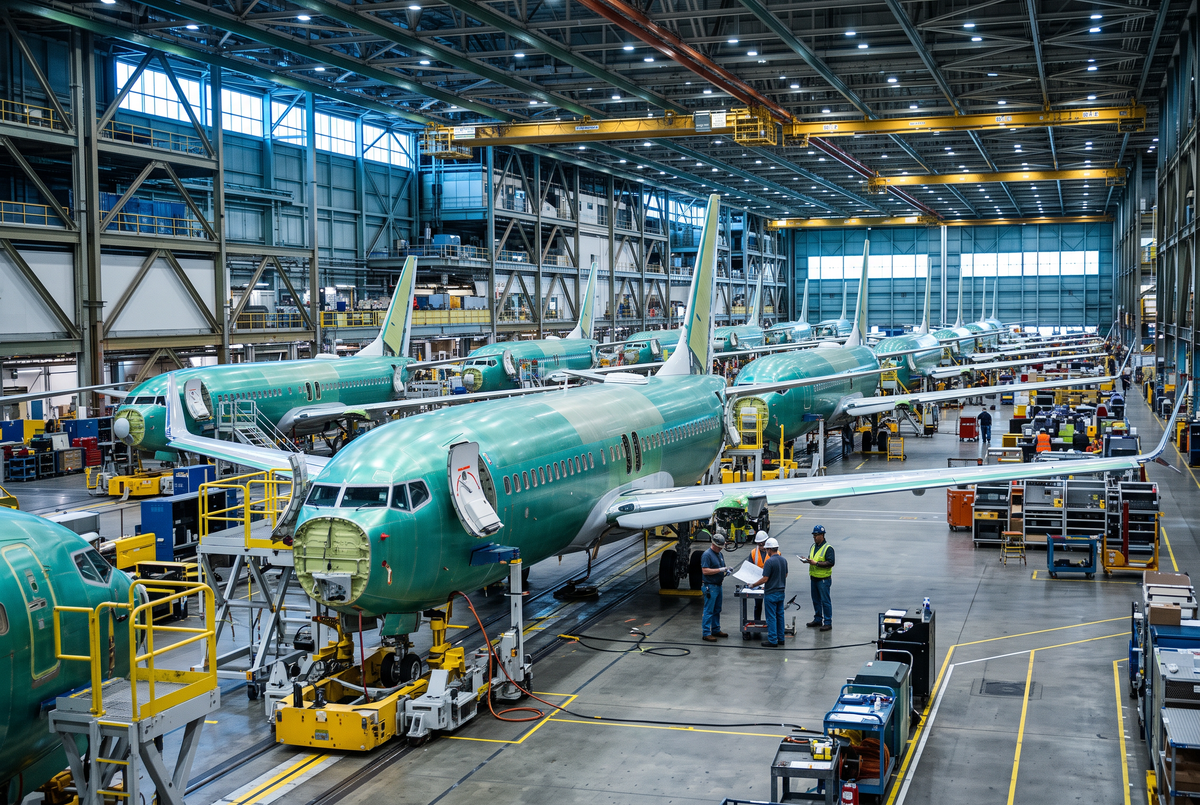
The shift was not subtle: management pushed a step up to 52 airplanes a month into the second half of 2027, and said stabilizing at 47 per month will take longer than expected. For investors betting on faster production-led cash generation, the delay was the headline they did not want to see.
Numbers on the scorecard
Boeing reported third-quarter revenue of $24.2 billion and a GAAP net loss of $116 million, versus a roughly $5.3 billion loss a year earlier, according to the company's public release. On a core non-GAAP basis, loss per share was $0.34, and operating margin improved to 1.5%. Operating cash flow was $1.5 billion, and free cash flow came in at $464 million, up from $238 million a year earlier.
The company said its total backlog rose to $745 billion, with the commercial backlog at $612 billion, and Commercial Airplanes delivered 161 planes in the quarter, 124 of them 737s. Commercial Airplanes revenue was $10.7 billion, down 3% year over year, and the unit posted a negative operating margin of 6.5%.
Production timing is the new pivot
The market reaction was driven by timing, not the topline. On the earnings call, management said proving out a stabilized 47-per-month cadence is taking longer than expected, full stabilization would run into next year, and the plan calls for a 52-per-month rate in the back half of 2027, according to the transcript. Executives pointed to the Renton wing backshop as the bottleneck slowing the ramp.
Management also said 737 deliveries totaled 124 in the quarter and that full-year deliveries are expected to fall short of a 500-airplane goal. The first 777X deliveries are planned for 2027, and the 787 is stable at about eight per month. Those timing notes matter because backlog converts to revenue as planes are delivered, and delivery cadence drives near-term cash flow.
Shares moved accordingly. Boeing stock fell about 10% on the day as investors absorbed a production acceleration they had expected, pushed further out.
Cash pathway and defense strength
Boeing laid out a multiyear free-cash-flow path on the call: about $2 billion in 2026, $3 billion in 2027, $6 billion in 2028, and $10 billion in 2029. That gives investors a clearer line of sight on where management expects cash generation to go as production ramps and other units improve.
Beyond commercial aviation, the Defense, Space & Security business grew revenue 15% to $7.9 billion on strength in classified programs, missiles and weapons, and the defense backlog expanded to a record $101 billion. Global Services revenue rose 4% to $5.6 billion. Cash and marketable securities stood at $20.7 billion, with debt unchanged at $45.9 billion.
The quarter also included roughly 300 net orders from airlines including Turkish Airlines, Ethiopian Airlines and Lufthansa, and Boeing noted the U.S. Navy selected it to design, build and deliver the F/A-XX next-generation fighter.
Why the backlog did not calm the market
At $745 billion the backlog is large and a clear signal of long-term demand, but the near-term story is execution. Investors who expected faster cash upside focused on the production timeline and how long it will take to push higher rates through the wing-shop constraint. Management's explicit timetable for 52 per month in the back half of 2027 reset those expectations.
That leaves Boeing in a mixed place: results and cash flow are improving, the 737 family is fully certified and orders keep coming, but the production cadence underpinning faster cash generation is the critical gating item. How quickly the Renton bottleneck clears will decide whether the free-cash-flow path management outlined is reached on the schedule it set.