The War Isn't Over. OPEC+ Is Pumping Like It Is.
OPEC+ clawed back 2.04 million barrels a day in October to 97% of pre-war output while the war grinds on, but demand growth forecasts sit at just 180,000 barrels a day for 2026. The supply recovery is running a year ahead of the demand it needs.
OPEC+ got close to where it started. According to OPEC's monthly report, the group's crude output, counting Mexico and the UAE, rose 2.04 million barrels a day in October to 41.23 million barrels a day. That puts October at 97% of the 42.72 million barrels a day OPEC+ produced in February, before the US and Israeli strikes on Iran. The war is still on. The pumps are running anyway.
The headline number comes from Riyadh. Saudi Arabia told OPEC it pumped 10.56 million barrels a day in October, up from 8.37 million in September, a 26% jump to its highest level since before the conflict. Iraq hit a new war-time high near 4.9 million barrels a day, well above its agreed limits. Iran, meanwhile, pumped 1.91 million barrels a day, its lowest in roughly four decades, its exports blocked by the sanctions regime driving this war. The roster of who is producing more and who cannot produce at all tells the story of the ceasefire arithmetic better than any communiqué.
Here is the uncomfortable part. Nobody is asking for this oil. In the same report, OPEC kept its demand growth forecasts unchanged, after cutting them for six straight months. The organization now expects world oil demand to grow by just 180,000 barrels a day in 2026, a fraction of the 1.4 million barrels a day it was forecasting before the war began. The sharp rebound it is counting on, 2.55 million barrels a day, is not scheduled to arrive until 2027.
So the timeline does not line up. The supply recovery is nearly complete, and the demand recovery is a year away. OPEC+ is pumping today against a forecast that has not landed and may not land the way the organization hopes. If 2026 demand grows by 180,000 barrels a day while the group has clawed back 2.04 million barrels a day of output, the market is being fed more crude into a demand picture that did not ask for it. Either the demand forecast is too conservative, or the supply strategy is early, and only one of those is verifiable this month.
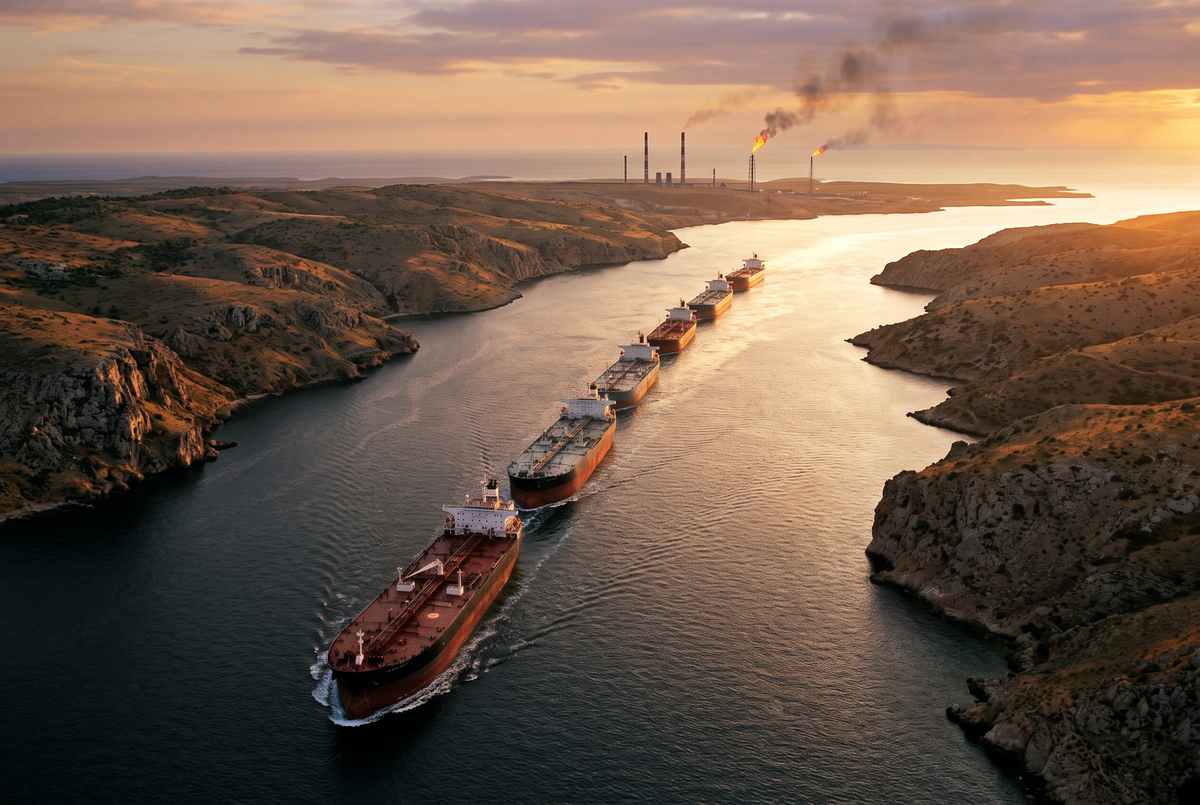
The market, for its part, is betting on something else entirely. Brent traded around $92.81 a barrel on Wednesday, up about 1.4% after dipping below $90 on Tuesday, but down roughly 21% since the start of the month. A 21% slide in a month during an active war is hardly what a shortage looks like. The market is betting that the shipping constraint will clear. The war's supply problem was always the war's shipping problem. The workarounds are real: ship-to-ship transfers, covert shuttle runs, the Red Sea pipeline. Every one of them erodes the premium the market pays for a strait it assumes will stay closed.
That assumption is being tested. At least 37 ships were attacked in October around the Strait of Hormuz, the highest monthly total since the war began. A truce may be hoped for, but the water is getting more dangerous, not less. If shipping risk stays elevated, the physical discount between embargoed and non-embargoed barrels widens, and the premium holds. If the workarounds keep scaling, the premium evaporates, and OPEC+ will have added supply into a market that has already stopped paying for scarcity.
The next checkpoint is close. OPEC+ meets Nov. 29 to set its 2027 output targets, and the capacity assessment that underpins those targets is being done in real time. The numbers on the table will be October's: near-full recovery of output, demand growth expectations cut to a trickle, and a price that has given back a fifth of its value in a month. The group has to decide whether it is managing for the war it has or the peace it expects.
The forecasts point one way and the pumps point the other. EIA expects Brent spot prices to remain near $100 per barrel for the remainder of this year if supply constraints persist, which would imply the market still half believes in the shipping constraint. But the direction of travel is clear enough to be uncomfortable for the producers. They have rebuilt 97% of their output. They are waiting for a demand rebound that arrives in 2027, in a market pricing the end of a war that has not ended. Pumping 41 million barrels a day into that bet is the bet itself.