TSMC's Sixth Straight Record: What a $46.7 Billion Quarter Reveals About the AI Economy's Real Foundation
TSMC reports its sixth consecutive record quarter with $46.7 billion in Q3 revenue, up 51% year-over-year. The results reveal the AI infrastructure buildout is not a sentiment trade but a fundamental capital allocation decision by the world's most cash-rich companies.

There is a number that Wall Street is sitting with this morning: 51. That is how many percent Taiwan Semiconductor Manufacturing Company's third-quarter revenue grew year-over-year, landing at NT$1.494 trillion - roughly $46.7 billion - when the company reported its full Q3 2026 results before US markets opened on Thursday. The EPS came in at NT$29.43. Net profit is expected to have surged approximately 64 to 65 percent from a year earlier, marking TSMC's sixth consecutive quarter of record earnings. In a week when a hotter-than-expected CPI print rattled bond markets and sent chip stocks lower, TSMC's results are a reminder that the AI infrastructure buildout is not a sentiment trade. It is a capital allocation decision being made by the most cash-rich companies on the planet, and it is not slowing down.
The Numbers Behind the Record
TSMC's Q3 revenue of $46.7 billion came in roughly 2 percent above the top of the company's own guidance range of $44.6 billion to $45.8 billion - a range that itself represented a 37 percent year-over-year increase at the midpoint. The company had already disclosed the revenue figure on October 8, so Thursday's earnings call was primarily about margins, profitability, and the forward outlook. Analysts polled by LSEG had expected net profit of approximately NT$740 to NT$746 billion, up 64 to 65 percent from the year-earlier period. Any result above NT$706.56 billion would set a new quarterly profit record - the eleventh consecutive quarter of profit growth for a company that was considered a cyclical semiconductor business just three years ago.
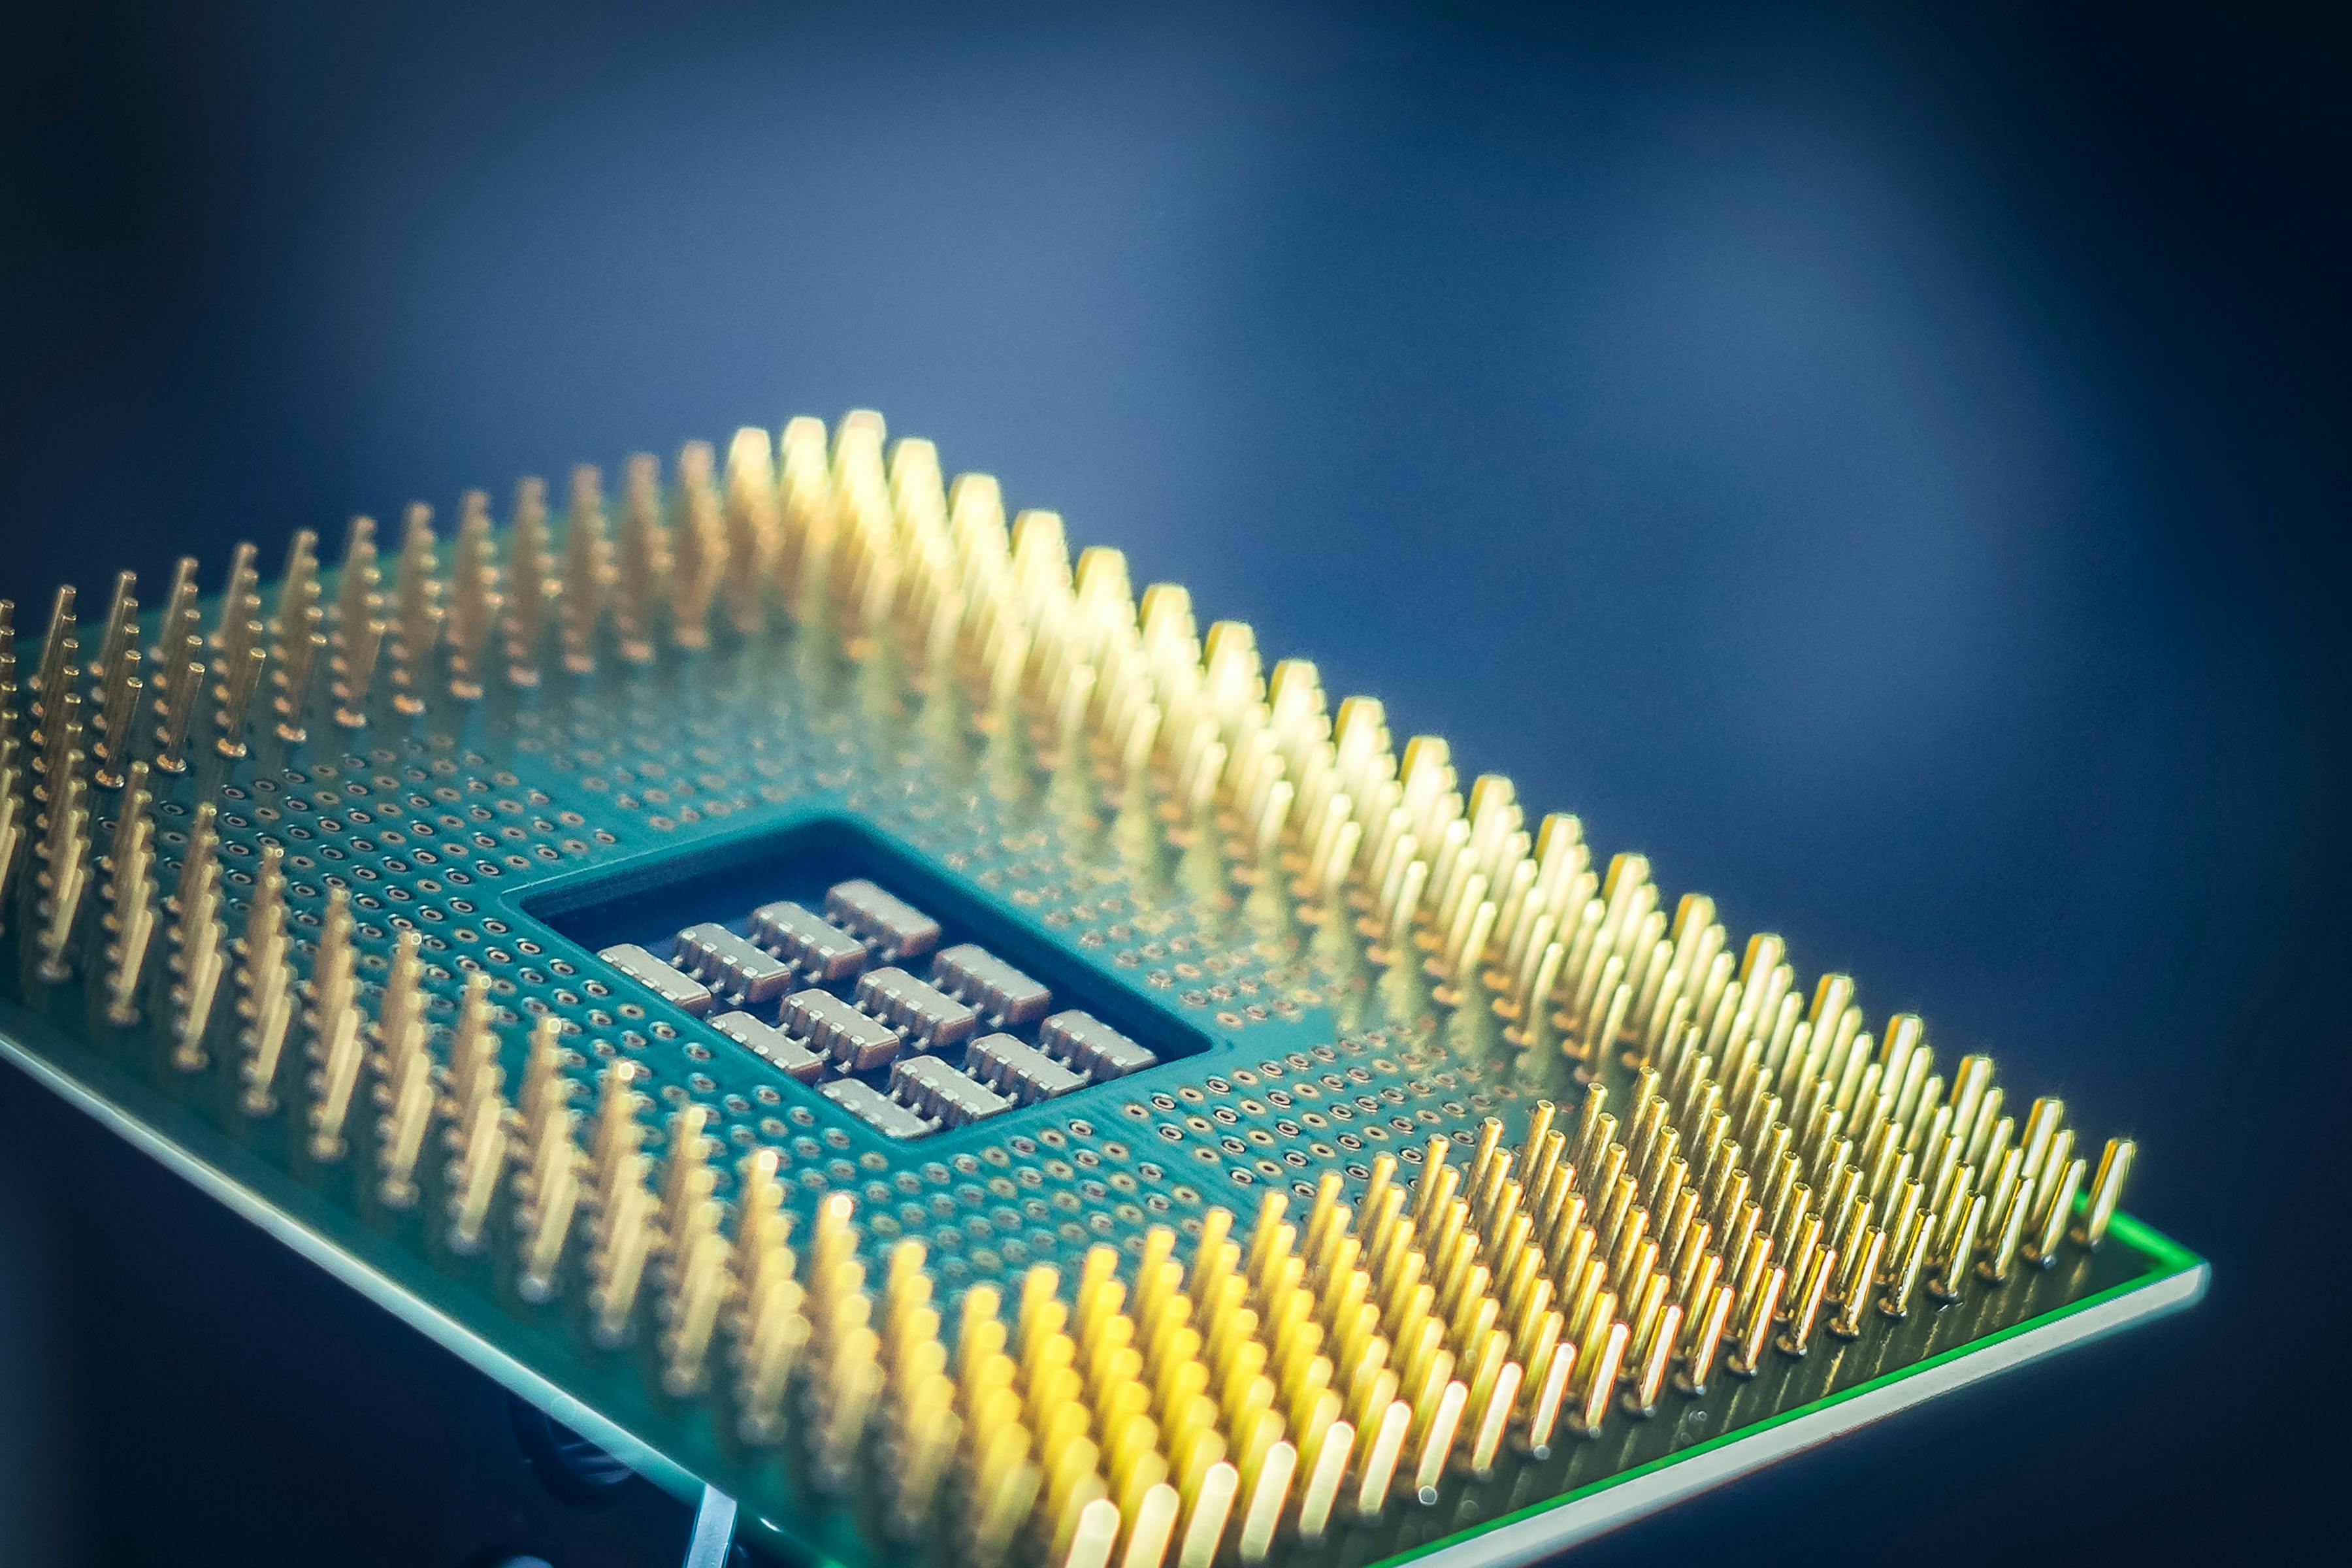
The gross margin picture is equally important. TSMC guided for Q3 gross margins of 65 to 67 percent. In Q2 2026, the company delivered 67.7 percent - a figure that reflected the pricing power that comes with being the only manufacturer capable of producing the world's most advanced chips at scale. The 2-nanometer node, which began ramping in Q3, is expected to account for approximately 11 percent of wafer revenue in the quarter, up from roughly 3 percent in Q2. That ramp matters because 2nm chips carry higher average selling prices and better margins than older nodes, providing a structural tailwind to profitability even as the company absorbs the costs of building new fabs in Arizona, Japan, and Germany.
AI Is Not a Trend - It Is a Customer Base
The most important number in TSMC's results is not the headline revenue figure. It is the share of revenue coming from high-performance computing - the category that includes AI accelerators, data-center CPUs, and the custom chips being designed by cloud providers for their own inference workloads. In Q2 2026, HPC accounted for approximately 66 percent of TSMC's total wafer revenue, up from 61 percent in Q1 and 60 percent a year earlier. That trajectory is not a coincidence. It is the direct result of Nvidia, AMD, Broadcom, Apple, and every major hyperscaler competing for capacity at TSMC's most advanced nodes.
TSMC's capex guidance for 2026 stands at $60 billion to $64 billion - a 48 to 58 percent increase over the prior year's spending. That capital is being deployed to add cleanroom space, install equipment for the 2nm and next-generation A16 nodes, and expand CoWoS advanced packaging capacity, which is the technology that stacks high-bandwidth memory directly onto AI accelerators. The company raised its full-year revenue growth forecast to slightly above 40 percent in US dollar terms at its July earnings call. Morgan Stanley analyst Charlie Chan expected TSMC to raise that guidance again on Thursday, to the low-to-mid 40 percent range, citing continued strong demand for 3nm chips and the accelerating 2nm ramp.
The Macro Headwind That Is Not Stopping the Buildout
Thursday's earnings call arrived in a complicated macro environment. The September CPI report, released on October 14, showed headline inflation accelerating to 3.7 percent year-over-year - above the 3.6 percent consensus - driven by a 9.1 percent surge in gasoline prices and a 0.4 percent increase in shelter costs. Core CPI rose 0.3 percent for the month and 2.6 percent annually, both above forecasts. The reaction was swift: Treasury yields moved higher, the probability of a Fed rate hike at the October 27-28 FOMC meeting rose, and chip stocks sold off. TSMC's ADRs were down approximately 3.4 percent on Wednesday ahead of the earnings release.
The tension between hot inflation data and record AI chip demand is the defining macro paradox of Q4 2026. Higher rates raise the cost of capital for the hyperscalers funding the AI buildout. They compress the present value of future earnings for every technology company. And they create a bond market alternative that did not exist when yields were near zero. But the companies ordering chips from TSMC - Microsoft, Google, Amazon, Meta, Nvidia - are not financing their AI infrastructure with borrowed money at the margin. They are funding it from operating cash flows that are themselves growing at double-digit rates. The rate environment creates headwinds for valuations. It does not change the fundamental demand signal that TSMC's order book represents.
What the Texas Expansion Tells You About the Long Game
One dimension of TSMC's results that deserves more attention than the quarterly numbers is the company's geographic expansion strategy. TSMC is building two fabs in Arizona - the first producing 4nm chips, the second targeting 2nm - as well as facilities in Kumamoto, Japan, and Dresden, Germany. The Arizona fabs have faced well-documented cost and timeline challenges, with production costs running higher than at TSMC's Taiwan facilities due to labor costs, supply chain differences, and the complexity of replicating a manufacturing ecosystem that took decades to build in Hsinchu.
The strategic logic behind the expansion is not primarily economic. It is geopolitical. The United States, Japan, and the European Union have all concluded that concentrating the world's most advanced chip manufacturing in a single geography - Taiwan - represents an unacceptable supply chain risk. The CHIPS Act subsidies, the Japanese government incentives, and the EU Chips Act are all designed to distribute that risk. TSMC is the only company capable of executing that distribution, which gives it extraordinary leverage in negotiating the terms of its expansion. The cost premium of non-Taiwan production is real. The strategic value of being the indispensable partner in every major government's semiconductor security plan is also real - and it is not reflected in any quarterly earnings figure.
What Investors Should Watch
The Q4 2026 guidance that TSMC provided on Thursday is the most important forward-looking data point in the AI supply chain this week. If the company guided for Q4 revenue above $48 billion - implying continued sequential growth - it would validate the thesis that the AI capex cycle has legs into 2027. If margins held above 65 percent despite the 2nm ramp costs and overseas fab dilution, it would confirm that TSMC's pricing power remains intact even as it absorbs significant capital expenditure. And if management raised the full-year revenue growth forecast above 40 percent, it would send a signal to every company in the semiconductor supply chain - from equipment makers like ASML to packaging specialists to power providers - that the demand environment is stronger than the macro headwinds suggest.
The broader lesson from TSMC's sixth consecutive record quarter is not about one company's financial performance. It is about the nature of the AI buildout itself. The companies spending hundreds of billions of dollars on chips, power, and data center infrastructure are not doing so because of a quarterly earnings cycle or a sentiment shift. They are doing so because they have concluded that AI capability is a durable competitive advantage - and that the cost of falling behind is higher than the cost of the capital being deployed. TSMC's order book is the most direct evidence available that this conclusion is not changing. The macro environment is complicated. The demand signal is not.